
 Freephone 24/7 Call: 0800 068 4015






I'm a property expert that still remembers the days when having broadband was a selling point! My articles cover issues that homesellers face in the UK and answer the questions we're all asking. I've bought and sold properties and helped others do the same, so my writing comes from years of experience.
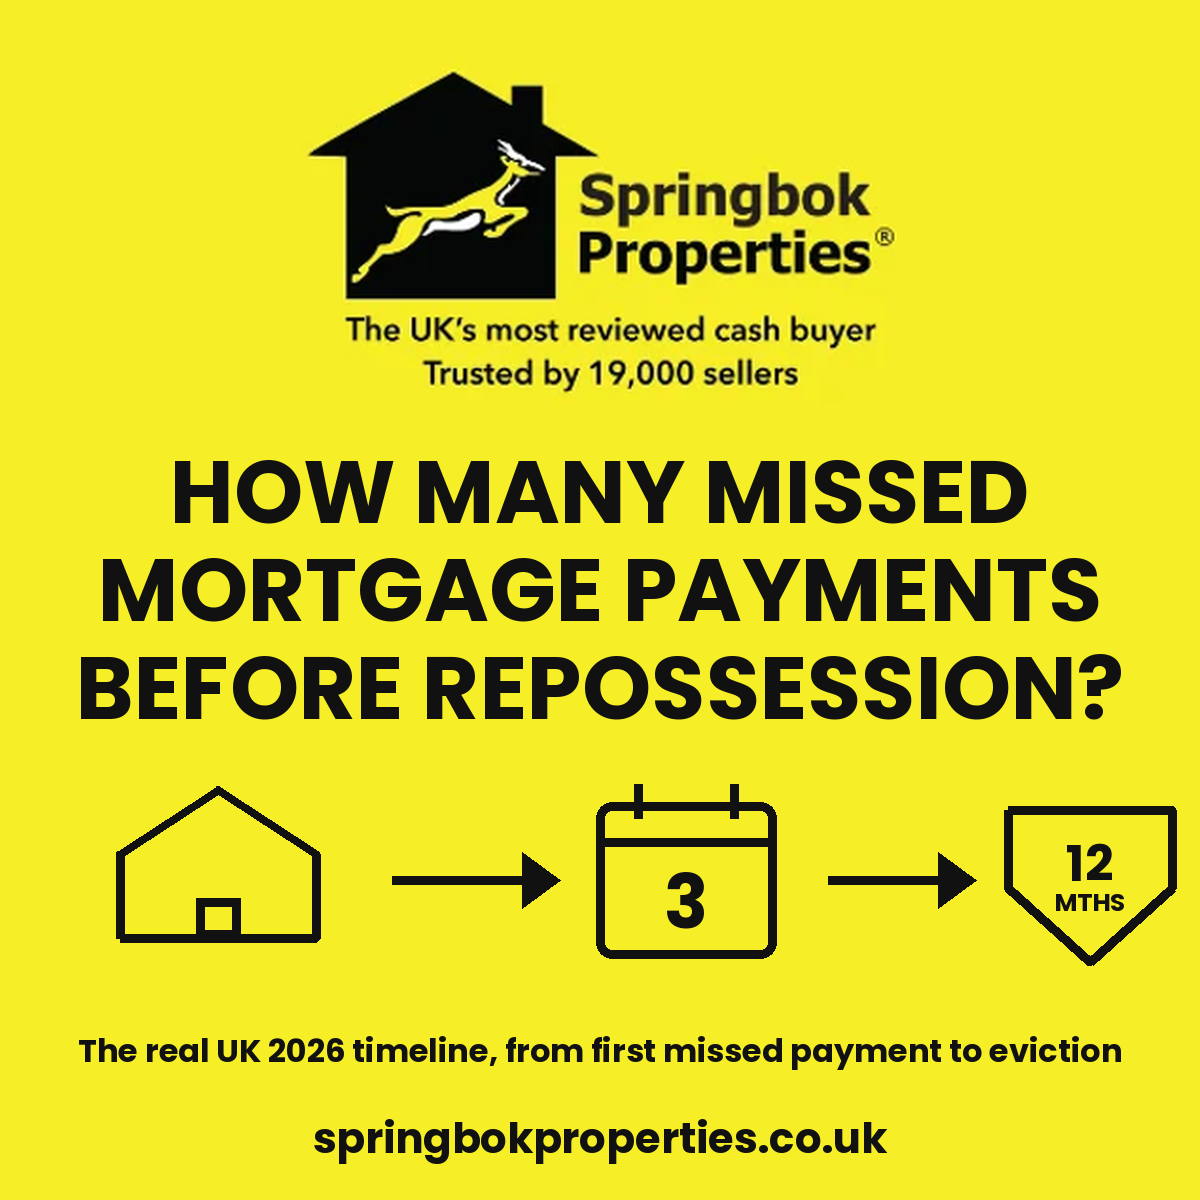
Read Full Bio >Most UK lenders start court action after three missed mortgage payments. Repossession is far slower: under the Mortgage Charter, signatory lenders will not remove you from your home within 12 months of your first missed payment.
Key takeaways
- Three missed payments is the point at which most lenders can begin possession proceedings — but only after the Pre-Action Protocol steps have been tried and failed.
- The Government’s Mortgage Charter, signed by 47 lenders covering around 90% of the mortgage market, commits them not to force you out of your home within 12 months of your first missed payment, except in exceptional circumstances.
- Between July 2023 and March 2026 the FCA recorded just 342 properties repossessed inside that 12-month window across the whole market.
- In Q1 2026 there were 79,110 homeowner mortgages in arrears of 2.5% or more of the balance — 0.91% of all homeowner mortgages, and 2% fewer than the previous quarter (UK Finance).
- 1,250 homeowner properties were taken into possession in Q1 2026 — up 3% on the quarter, but a fraction of the 2009 peak, when 216,400 mortgages were in arrears.
- You can sell at any point before the property is taken into possession, and the arrears are cleared from the sale proceeds. Selling almost always leaves you better off than a repossession sale.
If you have missed a mortgage payment, the question in your head is almost certainly a numbers question: how many can I miss before someone takes my house? The honest answer is that the number people quote — three — is the wrong number to fix on. Three is roughly when a lender becomes able to go to court. It is not when you lose your home. Under the current rules, the gap between those two things is usually more than a year, and almost everything that matters happens inside that gap.
How many missed mortgage payments before repossession in the UK?
Three missed monthly payments is the usual trigger for court action. The convention dates back to a November 2008 agreement between the major lenders and the government not to start possession proceedings unless the borrower had accrued three months’ arrears, and it has stuck. Some lenders will move at two months if a borrower has stopped responding altogether; most will not move at three if you are engaging with them.
| Stage | Typical timing | What actually happens |
|---|---|---|
| 1 missed payment | Days 1–30 | Lender contacts you, usually within 15 days. Recorded on your credit file. No repossession risk at this stage. |
| 2 missed payments | Months 1–2 | You are formally “in arrears”. Written notices arrive setting out the amount owed, your rights and the support available. |
| 3 missed payments | Months 3–4 | The point at which the lender may begin court action — but only if the Pre-Action Protocol steps have failed. |
| Court claim issued | Months 3–6 | You receive the claim form and a hearing date. You can still pay, negotiate or sell. |
| Possession hearing | 6–12 weeks after the claim | Judge decides. A suspended order — stay put, pay the instalment plus something off the arrears — is the most common outcome. |
| Possession order | Usually 28 days to leave | Outright orders normally give 14 or 28 days. The court can postpone if you have a credible plan, including a sale. |
| Warrant and eviction | +14 days’ notice minimum | Bailiffs must give at least 14 days’ notice of the eviction date. You can apply to suspend the warrant. |
Add it up and the realistic distance from first missed payment to losing the keys is 12 to 18 months in a case that goes all the way. Very few do.
Can my lender repossess after three missed payments?
Not straight away, and usually not for a long time after that. Three separate sets of rules sit between a missed payment and an eviction, and each one buys you time.
1. The FCA’s MCOB rules
Under the Financial Conduct Authority’s Mortgage Conduct of Business rules (MCOB 13), your lender must treat repossession as a last resort. Specifically it has to give you clear written information about what you owe and what your options are, consider any reasonable repayment proposal you make, and not start possession proceedings unless all other reasonable attempts to resolve the arrears have failed.
2. The Pre-Action Protocol
The Pre-Action Protocol for Possession Claims based on Mortgage Arrears, introduced by the Civil Justice Council on 19 November 2008, requires lenders and borrowers to try to reach an agreement before court. No proceedings should start while there is a real prospect of settlement. If your lender ignores it, the court can adjourn the case until it complies, and can penalise the lender on costs.
3. The Mortgage Charter
This is the protection most articles on this subject still miss. The Mortgage Charter, introduced in June 2023 and now signed by 47 lenders representing roughly 90% of the UK mortgage market, commits signatories not to force a borrower to leave their home without consent, other than in exceptional circumstances, in less than 12 months from the first missed payment. FCA data shows that between July 2023 and March 2026, only 342 properties were repossessed inside that window nationally.
How long does house repossession take in the UK?
Twelve to eighteen months from the first missed payment is the realistic range. The court stage alone typically runs three to six months: a claim is issued, a hearing is listed six to twelve weeks out, and if an order is made it usually gives 28 days.
Most hearings do not end with you losing the house. Judges have wide discretion under the Administration of Justice Acts to suspend possession where the borrower can clear the arrears over a reasonable period, and a suspended possession order — you stay, and pay the normal monthly payment plus an agreed amount off the arrears — is the usual result where someone turns up with a workable plan. If you breach a suspended order, the lender applies for a warrant, and bailiffs must give you at least 14 days’ notice of the eviction date. Even then you can apply to suspend the warrant.
How common is repossession in the UK right now?
Rare, and getting rarer. UK Finance recorded 79,110 homeowner mortgages in arrears of 2.5% or more of the outstanding balance in Q1 2026 — 2% down on the previous quarter, and just 0.91% of all homeowner mortgages. In the same quarter, 1,250 homeowner mortgaged properties were taken into possession, 3% up on Q4 2025 but still far below the long-run average.
| Measure | Q1 2026 | Q2 2009 (crisis peak) |
|---|---|---|
| Homeowner mortgages in arrears | 79,110 | 216,400 (homeowner and buy-to-let) |
| Share of homeowner mortgages in arrears | 0.91% | Roughly three times today’s rate |
| Homeowner possessions in the quarter | 1,250 | Multiples of the current figure |
| Quarter-on-quarter direction | Arrears down 2% | Rising sharply |
The point of these numbers is not reassurance for its own sake. It is that lenders repossess a very small number of homes because repossession is slow, expensive and loss-making for them. They would nearly always rather agree something with you. That gives you more negotiating room than most people in arrears believe they have.
What should I do first if I have missed a mortgage payment?
Two things, in this order, and both within days rather than weeks.
- Call your lender before they call you. Ask specifically about a temporary interest-only period, extending the term, a payment deferral, or capitalising the arrears. Lenders have far more discretion than their letters suggest, and a borrower who rings first is treated differently from one who does not answer the phone. Get any agreement confirmed in writing.
- Get free debt advice the same week. StepChange, Citizens Advice, Shelter and MoneyHelper are free, independent and used to exactly this conversation. An adviser can also check whether you are entitled to Support for Mortgage Interest, a government loan towards the interest on your mortgage.
If a possession hearing has already been listed, ask about the Housing Loss Prevention Advice Service. It provides free legal advice and representation in court to anyone in England or Wales at risk of losing their home, including through mortgage arrears, and there is a duty adviser at court on the day. You do not need to have arranged anything in advance.
Do not stop paying entirely while you wait for a decision. Partial payments are recorded, count in your favour at a hearing, and slow the arrears down. And do not ignore court paperwork — not attending a hearing is the single fastest route to an outright possession order.
Can I sell my house if I am in mortgage arrears?
Yes. You can sell at any point up until the property is taken into possession, and often after a possession order too, if the court agrees to postpone eviction because a sale is genuinely progressing. Your solicitor repays the mortgage and the arrears out of the completion money; anything left is yours.
Selling is worth considering seriously for one reason: you almost always get more for the house than the lender will. A lender selling a repossessed property is discharging a debt, not maximising a price. You are trying to protect whatever equity you have. Those are different jobs, and they produce different numbers.
| Route | Typical timescale | Price you get | Who controls it |
|---|---|---|---|
| Estate agent, open market | 4–6 months to completion | Full market value | You — but roughly one in four agreed sales falls through |
| Auction | 6–10 weeks | Variable; below market value is common | Shared — no guarantee it sells on the day |
| Genuine cash buyer | 7–28 days | Roughly 75–85% of market value | You — certainty is what you are buying |
| Repossession sale by the lender | Out of your hands | Whatever clears the debt; fees added to your balance | The lender |
Be clear-eyed about the trade-off. A fast cash sale means accepting less than the open market would pay — typically 75–85% of market value. That is a real cost, and it is only worth paying if speed and certainty are genuinely what you need. If you have twelve months of Charter protection and a lender willing to restructure, you may not need it at all. If you are weeks from a warrant with equity in the property, the arithmetic looks very different.
If you want to see where you would actually stand, our house sale calculator works out your likely net proceeds, and our guide to how long a sale takes once an offer is accepted sets out the open-market timeline. If a possession hearing is already listed, our page on stopping repossession and Dan’s guide to preventing home repossession cover the options in more detail.
What happens to my credit file — and to any shortfall?
Each missed payment is recorded on your credit file and stays there for six years from the date it was registered. A repossession stays for six years too, and it is one of the hardest marks to lend against: most mainstream lenders will not consider a new mortgage until it has dropped off, though specialist lenders may look at you sooner with a substantial deposit.
The bigger risk is a mortgage shortfall — when the sale does not raise enough to clear what you owe. The debt does not disappear with the house. In England and Wales a lender can pursue the capital element of a shortfall for up to twelve years, and the interest for six. This is the strongest practical argument for selling yourself rather than letting a repossession sale happen: a better sale price means a smaller shortfall, or none at all. If you are in negative equity, get advice before agreeing to anything.
Mortgage arrears and repossession: frequently asked questions
How many missed mortgage payments before repossession in the UK?
Three. Most UK lenders will not begin court possession proceedings until you are at least three monthly payments in arrears, and only after the Pre-Action Protocol steps have failed. Repossession itself takes far longer — usually well over a year from the first missed payment.
Can my lender repossess my house after two missed payments?
It is very unlikely. Two missed payments puts you formally in arrears and triggers written notices, but the Pre-Action Protocol requires the lender to try to agree a repayment plan first. Court action at two months happens only where the borrower has stopped engaging entirely.
How long does house repossession take in the UK?
Typically 12 to 18 months from the first missed payment. Court action usually starts after three to six months of arrears, the hearing follows six to twelve weeks later, and a possession order normally gives you 28 days. Bailiffs must then give at least 14 days’ notice.
Can I sell my house if I am in mortgage arrears?
Yes. You can sell at any point until the property is taken into possession, and you can sell even after a possession order if the court agrees to postpone eviction. Your mortgage and the arrears are repaid from the sale proceeds by your solicitor on completion.
How long do missed mortgage payments stay on my credit file?
Six years from the date each missed payment is recorded. A repossession and any resulting mortgage shortfall also stay on file for six years, and the shortfall debt itself can be pursued for up to twelve years in England and Wales.
What happens if my house sells for less than I owe?
The gap is a mortgage shortfall and you still owe it. Lenders can chase a shortfall for up to twelve years for the capital in England and Wales. Selling on the open market usually leaves a smaller shortfall than a repossession sale.
The bottom line
Three missed payments is when your lender can start the legal process. It is not when you lose your home, and the difference between those two moments is usually more than a year. Use it: ring the lender, get free advice, and if selling turns out to be the right answer, sell on your terms while you still have terms to set.
