
 Freephone 24/7 Call: 0800 068 4015






I'm a property expert that still remembers the days when having broadband was a selling point! My articles cover issues that homesellers face in the UK and answer the questions we're all asking. I've bought and sold properties and helped others do the same, so my writing comes from years of experience.
Read Full Bio >A “we buy any house” company is the buyer itself — it purchases with its own funds, typically completing in 7 to 28 days at roughly 75–85% of market value. An estate agent never buys anything: it markets your home to find a third-party buyer, aims for full market value, and averages about 22 weeks.
Key takeaways
- They are not the same kind of business. An estate agent is your agent and owes you duties; a house buying company is the counterparty sitting on the other side of the table.
- “We Buy Any House” is a category, not a company. Multiple unrelated UK firms trade under near-identical names, and some sites using the phrase are lead-generation middlemen, not buyers.
- Speed: 7–28 days for a funded cash purchase versus roughly 22 weeks from listing to completion through an agent in England and Wales.
- Price: about 75–85% of open-market value from a house buying company; up to 100% through an agent, less a fee averaging 1.42% including VAT nationally in 2026.
- Certainty: TwentyEA recorded a 23.7% national fall-through rate in Q1 2026 — close to one in four agreed sales collapsing. A funded cash purchase removes the chain that causes most of them.
- Neither route is statutorily regulated for cash buying. NAPB membership and Property Ombudsman registration are voluntary, so check both on their own member lists.
What is the real difference between We Buy Any House and an estate agent?
The difference is not speed or price. It is who you are dealing with. An estate agent is an intermediary you instruct: it acts for you, is paid by you on completion, and under The Property Ombudsman Code of Practice must pass on every offer it receives. A “we buy any house” company is a principal — it is buying your home for its own book, with its own money, to hold or resell.
That single structural fact explains almost everything else. An agent’s incentive is broadly aligned with yours, because a higher sale price means a bigger fee. A house buying company’s incentive is the opposite of yours on price, because every pound it does not pay you is a pound of its margin. This is not a scandal — it is simply the trade you are making, and you should price it honestly. Our guide to how “we buy any house” actually works walks through the mechanics step by step.
There is a second difference that catches people out. “We Buy Any House” is a search term, not a single business. Several unrelated UK companies trade under nearly identical names and web addresses, and a proportion of the sites ranking for the phrase are lead-generation middlemen that never buy anything — they capture your details and sell them on. Before you compare offers, confirm you are talking to an actual funded buyer.
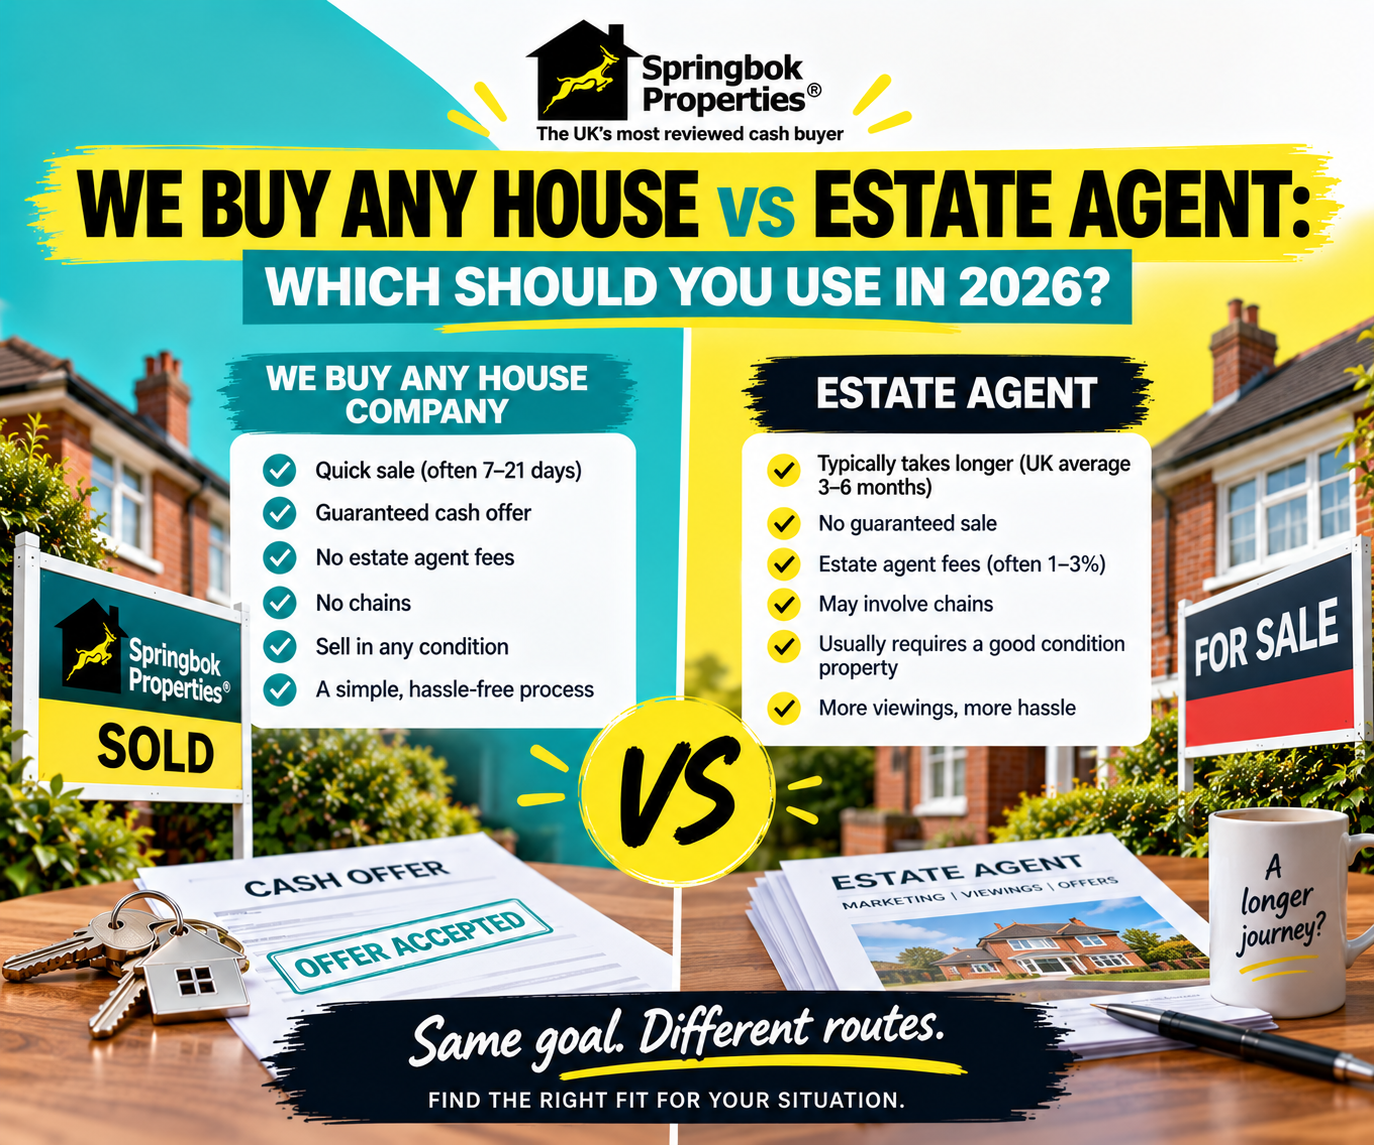
We Buy Any House vs estate agent: the at-a-glance comparison
| Factor | We Buy Any House company | High-street estate agent |
|---|---|---|
| Who buys your home | The company itself (principal) | A third party the agent finds |
| Whose side they are on | Their own — you are negotiating against them | Yours — they act as your agent |
| Typical time to completion | 7–28 days | ~22 weeks (about 5 months) |
| Price achieved | ~75–85% of market value | Up to 100% of market value |
| Cost to you | No fee; legal costs usually covered | ~1.42% inc VAT on average, plus conveyancing |
| Viewings | None, or one survey visit | Ongoing until a buyer is found |
| Chain risk | None — no onward chain | Yes, and it is the main cause of collapse |
| Fall-through risk | Low with a funded buyer | 23.7% nationally in Q1 2026 |
| Contract lock-in | None if reputable; avoid option agreements | Sole agency tie-in typically 8–16 weeks |
| Oversight | Voluntary: NAPB + TPO membership | Mandatory redress scheme membership |
How much less will a we buy any house company pay?
Expect roughly 15–25% below open-market value — an offer of about £187,500 to £212,500 on a £250,000 home. Any headline promise of 90% or more is almost always an opening number designed to be reduced later, a pattern we set out in how much below market value cash buyers really offer.
The honest comparison is not the two headline prices, though — it is what lands in your account. On that £250,000 home, an agent sale at full price loses roughly £3,550 in commission at the national average of 1.42% including VAT, around £1,500 in conveyancing, and about five months of carrying costs — mortgage interest, council tax, insurance and utilities — which at an illustrative £900 a month is another £4,500. That is close to £9,500 before you account for the risk of the sale collapsing and starting again.
So the real gap on a £250,000 house is usually £30,000–£40,000, not £45,000. You are buying roughly four months of your life back and a completion date you control. Whether that is good value depends entirely on what the delay is costing you — which is the whole question, and the reason the wider cash buyer, agent and auction comparison exists alongside this one.
Which is faster, and by how much?
An estate agent sale in England and Wales takes around 22 weeks from listing to completion. That splits roughly into two to four weeks of preparation, four to twelve weeks on the market finding a buyer, eight to sixteen weeks of conveyancing, and one to four weeks between exchange and completion.
A funded house buying company removes most of those stages. There is no marketing period and no buyer to find, because the buyer is already at the table with the money. What remains is a valuation, searches and the legal paperwork — which is why 7 to 28 days is realistic, with 14 to 28 the more common outcome. If you need to be out within a month, the agent route is not a slow option, it is effectively not an option.
How likely is each sale to actually complete?
TwentyEA recorded a national fall-through rate of 23.7% in the first quarter of 2026 — close to one in four agreed sales collapsing before completion, and the highest level in five years. Around 38% of those collapses happen within the first four weeks of a sale being agreed.
Almost all of that risk comes from things an agent cannot control: a buyer’s mortgage falling through, a survey renegotiation, or someone four links up a chain changing their mind. A genuinely funded cash purchase removes the chain entirely. It does not remove all risk — an underfunded buyer can still fail, which is exactly why proof of funds matters more than the headline offer.
What can go wrong with the We Buy Any House route?
The model is legitimate; parts of the sector are not well policed. These are the failure modes specific to house buying companies rather than to agents:
Price chipping before exchange. The offer is cut days before exchange, when you are committed and have nowhere to go. A genuine buyer reduces only on evidence — a survey finding or a legal defect — and confirms it in writing early.
Lead-generation middlemen. The “buyer” is a marketing site that sells your details to a panel. Ask directly: do you buy with your own funds, and can you evidence them?
Option or exclusivity agreements. A contract that stops you selling to anyone else for a fixed period, sometimes months. Never sign one.
Any fee payable by you. NAPB members are barred from charging sellers anything upfront — no survey, valuation or admin fee. A request for money before completion is disqualifying.
Offers of 90%+ of market value. The arithmetic does not work for a genuine buyer. It is a hook, and it is reduced later.
Our fuller breakdown of we buy any house scams and red flags covers each of these in detail, and whether these companies charge fees sets out what you should and should not be asked to pay.
What can go wrong with the estate agent route?
The agent risks are less dramatic and more expensive in aggregate. A sole agency tie-in of 8 to 16 weeks means a poorly performing agent can hold your property off other agents for months. Fees are negotiable but frequently are not negotiated — a 0.2 to 0.4 percentage-point reduction is realistic for most sellers who simply ask. And the headline commission is rarely the whole bill: the hidden costs of selling with an estate agent covers EPCs, premium listings, withdrawal fees and referral arrangements.
There is also the compounding cost of time. Every month unsold is another mortgage payment, another council tax bill, and — in a soft market — a rising chance you reduce the asking price anyway. A price cut in month four often costs more than the certainty you could have bought in week one.
How do you check either one is genuine?
- For a house buying company: check the National Association of Property Buyers member list directly — not the logo on their website — and confirm The Property Ombudsman registration. Note that TPO is a redress scheme, not a regulator: it states it cannot fine firms or dictate how they trade.
- Ask for proof of funds before you discuss price, and ask whether the company buys directly or passes leads to a panel.
- Check Companies House for the trading history of the exact legal entity named on the paperwork, not the brand on the advert.
- For an agent: confirm which redress scheme they belong to — it is a legal requirement — and read the contract for the tie-in length, the notice period, and any clause entitling them to a fee if you later sell to a buyer they introduced.
- Get both numbers before you decide. Ask three local agents what price would secure a sale within four weeks. If that reduction is smaller than the cash discount, the agent route may deliver both speed and more money.
Which route should you choose?
Choose an estate agent when you have no fixed deadline, the property is straightforward and mortgageable, and the last 15–20% of the price matters more to you than the completion date. Most sellers, most of the time, belong here.
Choose a house buying company when a certain completion date is worth more than the last slice of the price: a repossession deadline, a probate property draining money, a broken chain, an inherited house 200 miles away, a divorce settlement, or a property no lender will touch. In those situations the discount is not a loss so much as the price of ending the problem.
Where does Springbok fit in?
Springbok Properties is unusual in the market because it operates both models. Our We Buy Any House service is a direct cash purchase with a fixed completion date, and our Fixed Price service markets the property properly for full value with a capped, transparent fee. Springbok Properties Ltd is registered at Companies House (company no. 09045757), regulated by The Property Ombudsman and a member of the National Association of Property Buyers.
The practical advice is the same whoever you use: get both numbers in front of you before you commit to either. You can see what Springbok sellers say about how each route worked out for them, and our complete guide to selling a house fast covers every option including auction and part-exchange.
We Buy Any House vs estate agent: frequently asked questions
Is We Buy Any House a single company?
No. “We buy any house” is a category term, not one business. Several unrelated UK firms trade under near-identical names and web addresses, and some sites using the phrase are lead-generation middlemen that sell your details rather than buy your home.
Do I pay a we buy any house company anything?
You should pay nothing. National Association of Property Buyers members are barred from charging sellers any upfront cost — no survey, valuation or administration fee — and most genuine buyers also cover your legal fees. Any request for money before completion is a red flag.
Will an estate agent always get me more money?
Usually, but not always net. An agent aims for full market value and charges about 1.42% including VAT nationally, yet you also carry the mortgage, council tax and bills for roughly 22 weeks and accept a one-in-four chance the sale collapses.
Does the Property Ombudsman regulate house buying companies?
No. The Property Ombudsman is a redress scheme, not a regulator, and it states it cannot fine firms or dictate how they trade. The NAPB is a voluntary trade body. Neither is statutory regulation, so verify membership on their own member lists.
Can a we buy any house company reduce its offer before completion?
It can, and the weaker operators do — chipping the price days before exchange when you are committed. A genuine buyer reduces only on evidence such as a survey or a legal defect, and confirms the figure in writing early rather than at the last moment.
Which route is right if I need to move within a month?
A cash purchase. An estate agent sale averages about 22 weeks from listing to completion in England and Wales, so a one-month deadline effectively rules it out. A funded house buying company can complete in 7 to 28 days on a date you set.
Written by Dan Green, Springbok Properties. Last updated 4 September 2026.
